Global Smartphone Shipments Market Share (%)
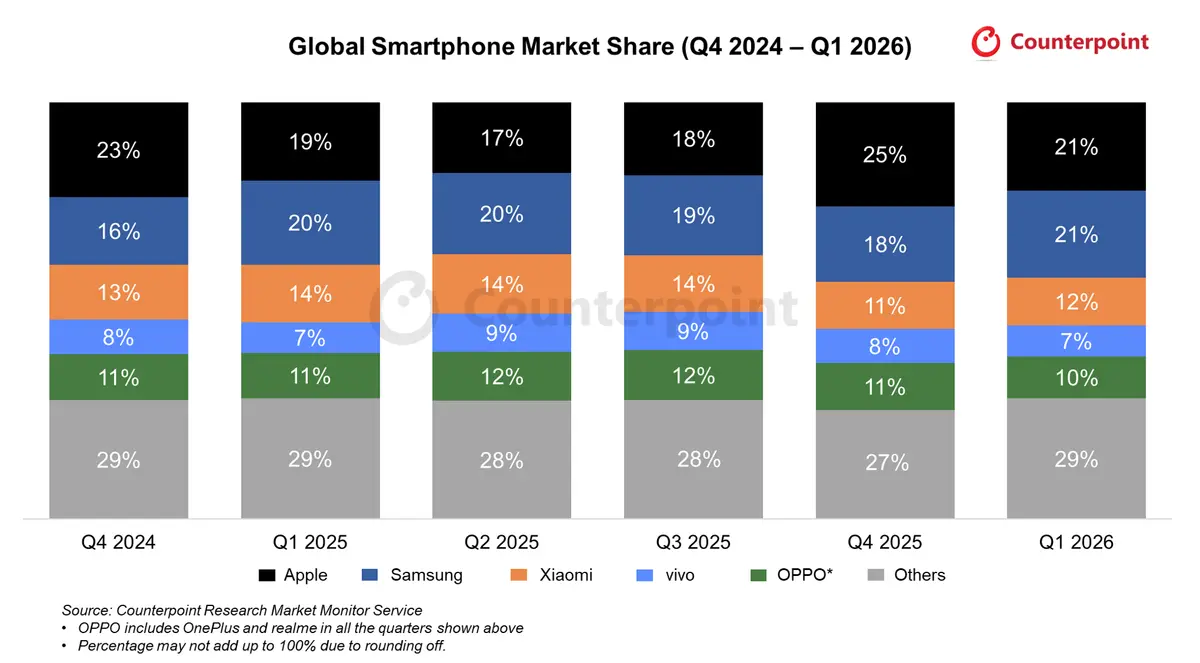
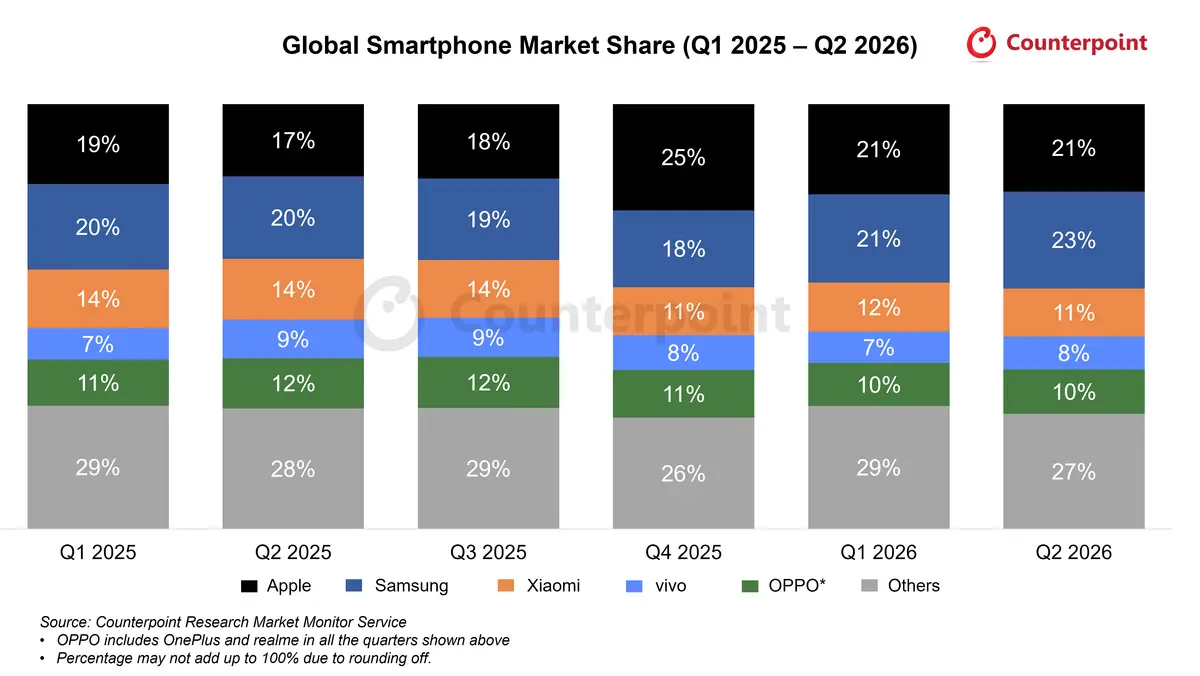
| Q1 2025 | Q2 2025 | Q3 2025 | Q4 2025 | Q1 2026 | Q2 2026 | |
| Apple | 19% | 17% | 18% | 25.0% | 21.2% | 21% |
| Samsung | 20% | 20% | 19% | 18.1% | 20.8% | 23% |
| Xiaomi | 14% | 14% | 14% | 11.3% | 11.5% | 11% |
| vivo | 7% | 9% | 9% | 8.2% | 7.4% | 8% |
| OPPO | 7% | 8% | 8% | 8.0% | 7.6% | 8% |
| Others | 32% | 32% | 32% | 29.3% | 31.5% | 27% |
MARKET HIGHLIGHTS
- The global smartphone market declined by 7% YoY in Q2 2026 as the memory shortage deepened and memory prices continue to rise. However some OEMs frontloaded shipments in anticipation of further component price hikes and logistics cost escalation, resulting in a milder-than-expected market decline.
- Developed regions showed more resilience against ongoing crisis due to more exposure to premium segment as they are better positioned to absorb component inflation. NAM (North America) was the only region to witness 6% YoY growth as to high premium penetration and carrier-led financing provided OEMs greater pricing flexibility. Even Western Europe also remained stable as it registered just 1% YoY decline.
- Samsung reclaimed the global leadership position with a 23% market share and growing 9% YoY, as pricing and competitive dynamics in certain regions worked in its favor.
- Apple recorded double digit growth 13% YoY and its highest Q2 market share (21%) driven by the continued strength of the iPhone 17 series which remained the top-shipped global model, alongside resilient demand in several key markets. It was also the only major OEM to avoid smartphone price hikes during the quarter.
- Xiaomi recorded the steepest decline among the top five smartphone brands, with shipments falling 26% YoY in Q2 2026. Its greater exposure to entry- and mid-tier segments left the company particularly vulnerable to rising memory costs, repeated device price increases and weakening affordability across several emerging markets.
- vivo smartphone shipments declined 21% YoY in Q2 2026, as pressure on lower price segments outweighed resilience in its mid-to-premium portfolio. Rising component costs and weaker demand across price-sensitive markets continued to weigh on overall shipment performance.
The global smartphone market share numbers are from:
Market Monitor - OEM Shipment by Region and Countries, Q2 2026
Excel File | Published Date: August 2026
This report is part of a series of market monitor reports which track the mobile handset market: Smartphone and Feature Phone shipments every quarter for more than 140 brands covering more than 97% of the total device shipments in the industry.
Read more Contact us